About the EMI Calculator
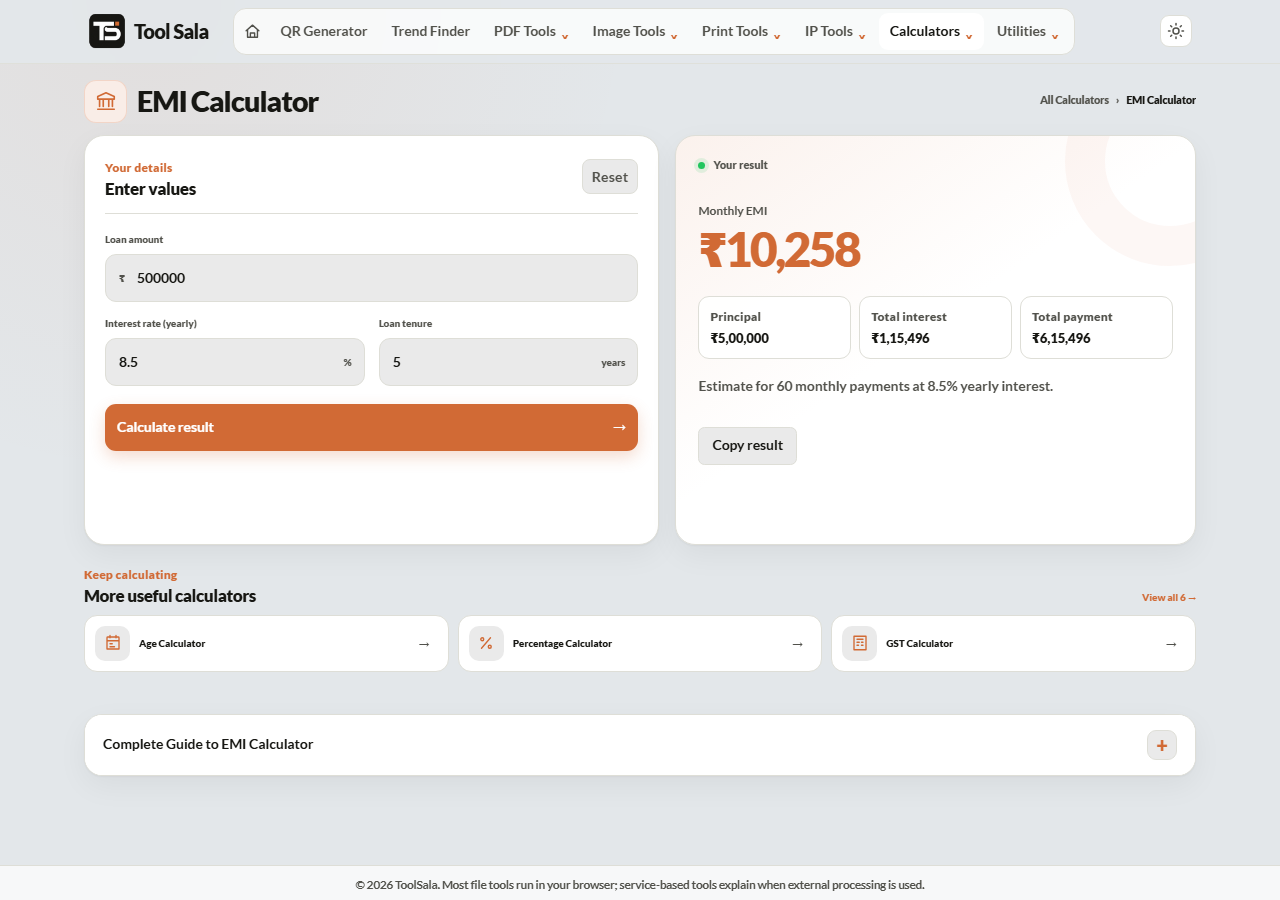
This free EMI calculator shows exactly what a loan will cost you every month. Enter the loan amount, the yearly interest rate and the tenure in years, and you get the monthly EMI along with the total interest you will pay over the full term.
Most people only look at the EMI. The number that actually matters is the total interest — on a 20-year home loan it can come close to the loan amount itself. Seeing both figures side by side is what makes the decision clear.
How to calculate your EMI
- Enter the Loan amount in rupees — the amount the bank actually pays out, not the property price.
- Enter the Interest rate (yearly) as a percentage. Use the rate on your sanction letter, not the advertised “starting from” rate.
- Enter the Loan tenure in years.
- Click Calculate result.
- Use Copy result to paste the figures into a message or spreadsheet.
The formula behind it
Banks in India use the standard reducing-balance formula:
EMI = P × r × (1 + r)ⁿ ÷ ((1 + r)ⁿ − 1)
Here P is the principal, r is the monthly interest rate (yearly rate ÷ 12 ÷ 100) and n is the number of monthly instalments. Every EMI is the same amount, but the split changes: early instalments are mostly interest, later ones are mostly principal. That is why paying off a loan in year two saves far more than paying it off in year fifteen.
What tenure does to your loan
Take ₹30,00,000 at 9% interest. Stretching the tenure lowers the EMI but raises the total cost sharply:
- 10 years — highest EMI, lowest total interest.
- 20 years — EMI drops a lot, total interest roughly doubles.
- 30 years — EMI drops a little more, total interest becomes brutal.
Run those three tenures through the calculator yourself. The jump between 20 and 30 years is usually the moment people change their mind.
Before you sign
- Processing fees, insurance and legal charges are not part of the EMI. Ask for the total cost in writing.
- A floating rate means your EMI or tenure will change later. This calculator assumes a fixed rate.
- Keep total EMIs under roughly 40% of your take-home pay, or the loan will control your month.
- Even one extra EMI a year cuts a 20-year loan by several years.
EMI Calculator FAQs
Is this EMI calculator free?
Yes. No account, no signup, and no limit on how many times you calculate.
Does it work for home, car and personal loans?
Yes. The reducing-balance formula is the same for all of them. Only the interest rate and tenure differ — home loans are longest and cheapest, personal loans shortest and costliest.
Why is my bank’s EMI slightly different?
Banks round figures, may charge interest from the disbursement date rather than month start, and sometimes add insurance into the EMI. Expect a difference of a few rupees to a few hundred.
Should I choose a longer tenure for a smaller EMI?
Only if the shorter EMI genuinely does not fit your budget. A longer tenure lowers the monthly payment but increases the total interest a lot. Compare both in the calculator before deciding.
How much do I save by prepaying?
Prepayment reduces the principal, so all future interest on that amount disappears. The earlier you prepay, the bigger the saving. Recalculate with the reduced amount and remaining years to see it.
Is my data stored anywhere?
No. The calculation runs in your browser. Nothing you type is sent to a server or saved.
Related online tools
- SIP Calculator — see what the same monthly amount could grow to if invested instead.
- Percentage Calculator — quick interest and share calculations.
- GST Calculator — add or remove GST from any amount.
- Invoice Generator — create a professional invoice PDF.
- All calculators — the full list.